Significant changes have been made to the government's proposed pension reform following strong reactions and reservations expressed by social partners, as the Ministry of Labour seeks broader consensus before submitting the bill to parliament.
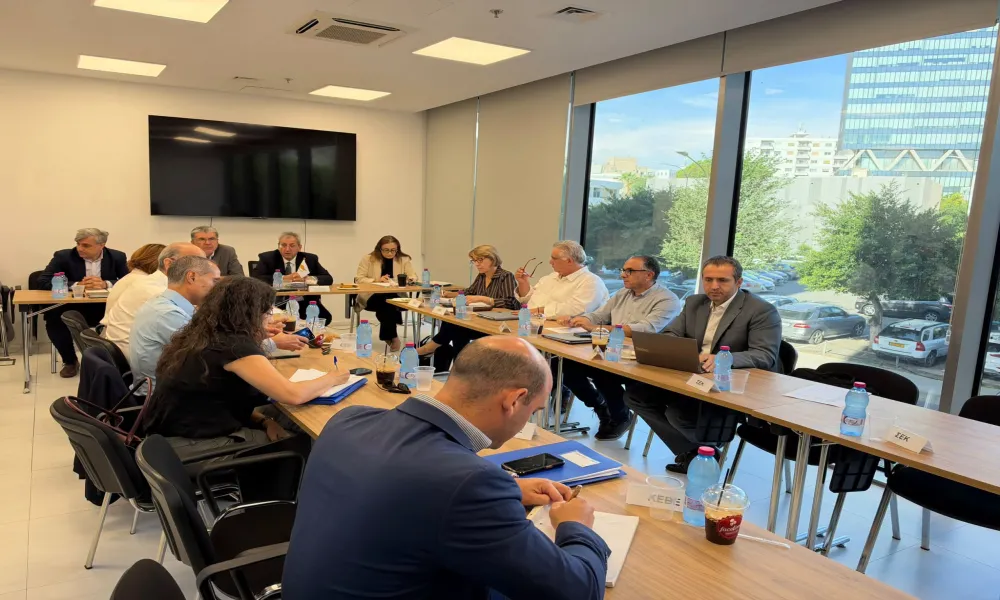
During Monday's meeting of the Labour Advisory Body, the ministry presented three major amendments:
- Extension of the transition period from five to 15 years.
- Faster implementation of pension increases, over three years instead of five.
- Improved provisions for widow's and disability pensions.
Transition period extended to 15 years
The most significant change concerns the extension of the transition period from five to 15 years.
According to information obtained by Politis, the protection mechanism ensuring pensioners receive whichever pension is higher under either the existing or new calculation method will remain in place until 2041.
This means that neither current nor new pensioners retiring before then are expected to see their pensions reduced.
The government is also revising the supplementary pension coefficient. During the transition period between 2027 and 2041, the new calculation formula will use a coefficient of 1.25%, while comparisons will continue to be made with the existing 1.5% coefficient, with pensioners receiving whichever amount is more favourable.
From 1 January 2042, a coefficient of 1.35% will apply to all pensioners, replacing the previously proposed 1.34%, and the comparison mechanism between the old and new systems will end.
Labour Minister Yiannis Panayiotou said the extension of the transition period appears to address concerns over potential future contribution increases.
Pension increases to be paid faster
Another key amendment concerns the recalculation of existing pensions.
Rather than being phased in over five years, increases would now be fully implemented within three years.
Under the revised proposal:
- 30% of the increase would be paid in 2027.
- A further 30% would be paid in 2028.
- The remaining 40% would be paid in 2029.
The original bill proposed distribution over five instalments, with the final 20% not paid until the fifth year.
No reductions in pension examples presented
During Monday's meeting, officials presented six illustrative examples covering insured persons with between one and six insurance units.
According to the ministry's presentation, none of the examples resulted in reductions to either the basic or earnings-related pension under the new system.
Changes to widow's and disability pensions
The revised reform package also includes amendments affecting widow's and disability pensions.
Under the proposal, the first widow's or disability pension would continue to be paid at:
- 100% of the basic pension component.
- 60% of the earnings-related component.
For any subsequent widow's or disability pensions, payments would be set at 60% of both components.
The minister described agreement on the three main changes as a step forward and said the government remains willing to examine additional proposals from social partners.
He cautioned, however, that some aspects of the reform cannot be altered because of either policy considerations or the overall design of the government's proposal.
Actuarial review and investment policy
Beyond changes to pension calculations, the revised bill strengthens oversight of the Social Insurance Fund.
An actuarial study assessing the fund's sustainability is scheduled for 2032, alongside a review of its investment strategy. Further reviews would then take place every three years.
The legislation will also provide for:
- A formal investment policy.
- The establishment of a management body.
- The creation of a supervisory mechanism.
The government estimates investment returns of between 3% and 4% through 2032.
As part of these changes, provisions allowing potential contribution increases after 2031, or a reduction of the coefficient from 1.34% to 1.25%, are being removed because the law would require an investment policy to be in place by 2032.
After 2042, further increases to the 1.35% coefficient may be considered depending on the fund's investment performance.
For dividend income, contribution calculations will be capped at two insurance units rather than the maximum insurable earnings ceiling.
Bill headed to Cabinet
Social partners are expected to seek additional clarifications at another Labour Advisory Body meeting on Thursday, with their final positions likely to be determined later this month.
Despite ongoing consultations, the government remains committed to submitting the bill to the Council of Ministers for approval as soon as possible before forwarding it to parliament.
Discussions with social partners will continue every Monday and Thursday, while any further agreed amendments can still be incorporated after the bill is formally tabled.
The government's objective remains to implement the new pension system on 1 January 2027.
According to the minister, any technical issues arising after parliamentary approval can be addressed through existing mechanisms.
He stressed that the reform must balance the sustainability of the Social Insurance Fund, higher pensions and the long-term health of the public finances.