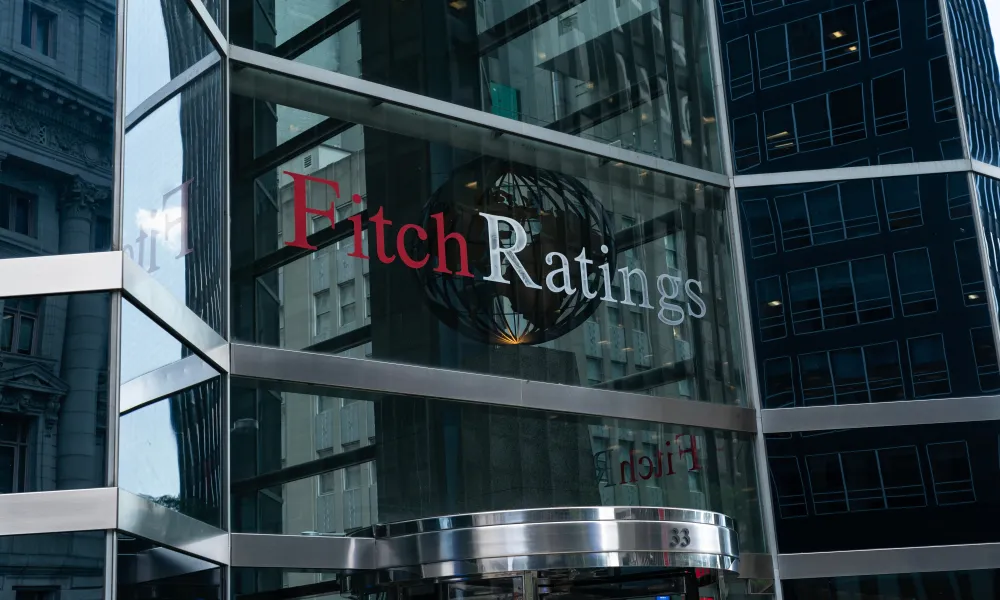


Fitch Ratings has upgraded Cyprus’s long-term credit rating to «A» from «A-», maintaining a stable outlook.
The agency says the decision reflects Cyprus’s continued strong fiscal performance, rapid public-debt reduction and large fiscal surpluses that are significantly stronger than those of other countries. The upgrade also reflects strong macroeconomic performance, supported by the economy’s increased diversification.
Cyprus’s rating is also supported, Fitch says, by per-capita income above the median for «A»-rated countries, strong fiscal performance and the credibility of policymaking, underpinned by the country’s membership of the European Union and the eurozone.
These strengths are balanced by governance indicators that are slightly weaker than those of other countries, external-economy vulnerabilities and regional political tensions related to the division of the island.
Surpluses and rapid debt reduction
Explaining the main factors behind the upgrade, Fitch estimates that Cyprus will continue to outperform fiscally and retain the eurozone’s highest general-government surplus: 3.2% of GDP in 2026, unchanged from 2025. The performance will be supported by spending restraint and continued strong public-revenue performance in a favourable macroeconomic environment, according to the agency.
«We forecast fiscal surpluses to average 2.9% in 2027-2028», Fitch says. It adds that the authorities remain committed to prudent fiscal policies, which it considers credible given broad consensus on maintaining fiscal stability, despite significant scope to increase spending.
The agency does not expect significant additional fiscal support to offset higher energy prices beyond measures already enacted, which it estimates at 0.2% of GDP. It also notes that tax reform has not substantially reduced revenues so far.
Central-government debt is expected to fall rapidly to 46.3% of GDP in 2026, from 52.4% in 2025, and further to 36.6% by 2028, Fitch estimates. The decline is attributed to high primary surpluses and strong nominal growth.
«This implies an impressive 77-percentage-point fall from its 2020 peak, one of the sharpest declines globally, putting the debt ratio well below the “A” median of 59.5%», the agency says. After 2028, the fall in debt is expected to slow as surpluses are used to repay intra-government debt owed to the Social Insurance Fund.
Interest expenditure stood at just 1.1% of GDP in 2025. Fitch forecasts an increase to 1.5% in 2028 because of refinancing at higher rates, but expects the cost to remain low by historical standards. «Cash reserves of 7.3% of GDP provide additional flexibility», it says.
Growth and the labour market
For 2026-2028, Fitch forecasts resilient growth of 3% in Cyprus’s GDP, above both the eurozone average and the median for «A»-rated countries. The momentum is driven by strong domestic consumption and the continued positive performance of the services sector, the agency says.
Risks related to the Middle East crisis have not materialised, Fitch notes, as the economy rebounded quickly after sentiment weakened in April-May.
Recent data revisions point to much stronger growth in 2022-2025 than previously estimated, averaging 6.6% annually. This, the agency says, highlights positive spillover effects from investment and the diversification of the services sector. GDP per capita has now converged with the eurozone average.
Cyprus has a broad investment portfolio which, together with rising productivity in key sectors such as information and communications technology (ICT), is expected to support continued strong growth over the medium term. Potential growth is estimated at 3%.
The labour market remains stable, with participation rates at historic highs and unemployment forecast to average just 3.8% over the forecast period, supporting private consumption.
Fitch highlights short-term risks centred on inflationary pressures and their effect on consumption. External vulnerabilities, including the large current-account deficit and low energy independence, will also remain a key medium-term challenge.
Harmonised inflation was 5.2% in September, up from just 0.9% in February, reflecting high dependence on imported fossil fuels and higher services prices. Wage pressures remain moderate, but are expected to increase moderately from 2027 as cost-of-living adjustments take effect, albeit at much lower rates than in 2022-2023. Fitch forecasts inflation averaging 4% in 2026 and 2.5% in 2027-2028, reflecting lower expected energy costs.
External balance and banks
Fitch expects the current-account deficit to remain large in 2026-2028, averaging 8.1% of GDP. The trade deficit is affected by higher energy costs and a moderation in the strong growth of services exports recorded in previous years.
The agency views the rapid recovery in tourism positively, following the slowdown after the outbreak of war in the Middle East. «As in previous years, steady foreign direct investment (FDI) inflows will fully finance the current-account deficit», it says. However, it warns that reliance on large capital inflows amid geopolitical and security risks, as well as possible shifts in investor sentiment, underlines a persistent vulnerability.
The banking sector remained resilient in the first half of 2026, with the system showing strong solvency, liquidity and profitability. The Common Equity Tier 1 (CET1) ratio stood at 25.5% in June 2026, the highest in the European Union, giving banks substantial buffers in the event of a cyclical economic downturn.
The non-performing loan (NPL) ratio remained low at 1.6% in the first half of 2026, compared with a peak of close to 45% in 2015. This, Fitch says, highlights significant progress in addressing past challenges.
Risks and possible upgrade factors
Fitch cites a sharp increase in the public-debt-to-GDP ratio, for example due to prolonged fiscal loosening, as a factor that could lead to a negative rating action. At the macroeconomic level, an external shock that would intensify external vulnerabilities and result in a prolonged slowdown in economic growth could also have a negative effect.
A rating upgrade could follow a reduction in vulnerability to external shocks, for example through a structural reduction in large current-account deficits and/or greater resilience to geopolitical shocks. A significant improvement in GDP per capita and governance indicators towards the levels of higher-rated peers is also listed as a possible upgrade factor.
Source: CNA