The government on Monday unveiled its plans for the reform of Provident Funds, setting an initial objective of extending coverage to 50%-60% of workers who currently do not belong to a Provident Fund, while keeping open the possibility of making participation compulsory in the future if that target is not achieved.
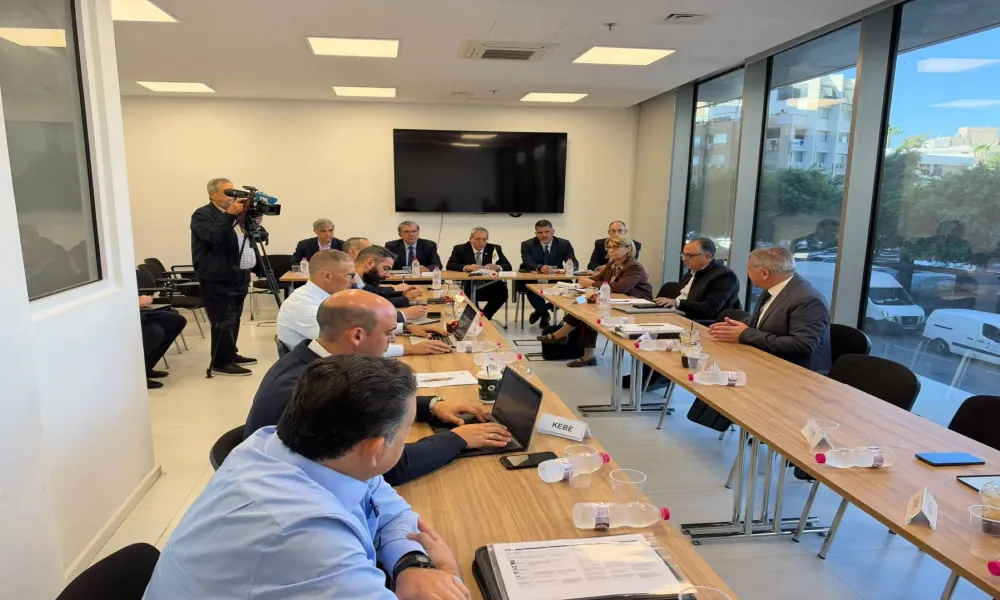
Following the submission last week of a comparative table outlining the positions of the social partners on Provident Fund reform, the government presented its proposal orally as a basis for discussion, acknowledging the differing views of employer organisations and trade unions.
The government's approach provides for the initial establishment of new Provident Funds on a voluntary basis, supported by strong incentives for businesses, with the aim of bringing 50%-60% of currently uncovered employees into the system.
According to the proposal, the effectiveness of the measure will be reviewed after three to four years. If the targets are not met, the possibility of moving to a mandatory system will remain on the table. An intermediate stage is also being considered, involving higher coverage targets but without the initial incentives offered to employers.
"If we do not reach the target that is set, Pillar Two will automatically become mandatory under the legislation that will be approved, and companies that join compulsorily will not benefit from the advantages granted to companies that joined voluntarily," the Labour Minister told parliament during discussions on the ministry's 2027 budget.
The minister also stressed that Provident Funds should function as a monthly supplement to pensions, rather than as a borrowing tool, in order to strengthen retirees' incomes.
1.5% contribution
According to information obtained by Politis, the ministry's proposal provides for an initial contribution of 1.5% from employers and 1.5% from employees.
The possibility was also raised of not increasing contribution rates in 2029, should the new Provident Fund plan be implemented, given the scheduled increase in contributions to the Social Insurance Fund.
As part of the broader reform, the ministry is also proposing a review of the operating framework of existing Provident Funds, particularly regarding lending rules. The creation of an independent supervisory authority is being considered, alongside implementation of the new system within three to four years. Issues such as staffing, funding and governance arrangements remain under discussion.
Particular emphasis is also being placed on the merger of smaller Provident Funds into larger and more sustainable structures, with the aim of reducing their number to around 130, lowering operating costs and improving the management of reserves.
The total number of pension funds in Cyprus has already declined significantly in recent years. According to figures published by the Central Bank in June, the total number of pension funds in Cyprus fell to fewer than 600 by the end of 2025, reflecting a decline of more than 30% over the previous five years.
As was highlighted during the discussions, strengthening the confidence of both employees and employers in the system will be crucial to the success of the reform, given the long-term nature of retirement savings.
Social partners unconvinced
The government's proposal, presented as a basis for discussion, has not satisfied the social partners.
Neither employer organisations nor trade unions appear to agree with the ministry's approach, with employers rejecting any possibility of compulsory participation and unions arguing that an initial voluntary model would have little practical value.
"We categorically disagree with the proposal because, as presented, it amounts to mandatory participation with a grace period. Our position remains that it should stay voluntary, supported by incentives from the state," Emilios Michael, deputy secretary-general of the Cyprus Chamber of Commerce and Industry (Keve), told Politis.
"There is no possibility that we will accept mandatory Provident Funds. We first want to hear what incentives the state intends to provide to extend employee coverage and only then can we discuss voluntary participation targets, percentages and timeframes," said Michalis Antoniou, director-general of the Employers and Industrialists Federation (Oev).
"For us, if Provident Funds are to fulfil their role in strengthening pension adequacy, they must be compulsory," said Sotiroula Charalambous, secretary-general of Peo, arguing that a voluntary approach would not achieve that goal.
"A voluntary scheme cannot be regarded as satisfactory," Andreas Matsas, secretary-general of Sek, told Politis. He pointed out that a voluntary arrangement is already envisaged under legislation relating to wage adequacy, with employers raising objections over its interpretation. "The regulation should provide for compulsory participation from the outset so implementation of the pension adequacy objective is not delayed," he said.
"Universal Provident Funds are not only desired by trade unions. Society as a whole wants them," argued Stelios Christodoulou, president of Deok. "If there is to be genuine reform, it must be compulsory, regardless of whether progress is made or not."
Economist and pensions specialist Akis Ioannides also supports making Provident Funds compulsory from the beginning.
"For this reform to be genuine, Provident Funds must be mandatory from the outset because a voluntary framework already exists," he said, while criticising the broader pension reform strategy. "It is a pre-election firework that will be lit by our generation and extinguished by younger generations," he added.
Disagreements over retirement age
During Monday's meeting of the Labour Advisory Body, disagreements also emerged between the trade unions and the Labour Ministry over the interpretation of legislation linking life expectancy to the retirement age.
Union representatives argued that an increase in life expectancy does not automatically result in an increase in the retirement age but instead triggers a process of social dialogue.
The ministry responded that the existing mechanism was introduced during the Troika period to safeguard the sustainability of the Social Insurance Fund. It said the mechanism operates automatically and only technical clarifications are needed for the relevant regulations to be issued.
The ministry further argued that any change to the mechanism would affect actuarial studies, noting that during the first five-year review the change in life expectancy amounted to less than one month and did not result in an increase in the retirement age.
Trade unions also expressed reservations about proposals for the voluntary extension of retirement to the age of 67.
Current legislation provides for the retirement age to increase by six months, provided life expectancy rises.
Speaking to Politis Radio, the Labour Minister left open the possibility that the retirement age could increase after 2028, while stressing that the actuarial study underpinning the pension reform currently assumes it will remain at 65.
He recalled that an agreement has existed since 2013 to review the retirement age every five years based on life expectancy. According to the minister, the previous two reviews did not result in any increase, while the next review is expected in 2028 or 2029.
Should the findings indicate an adjustment is necessary, the retirement age will be increased.