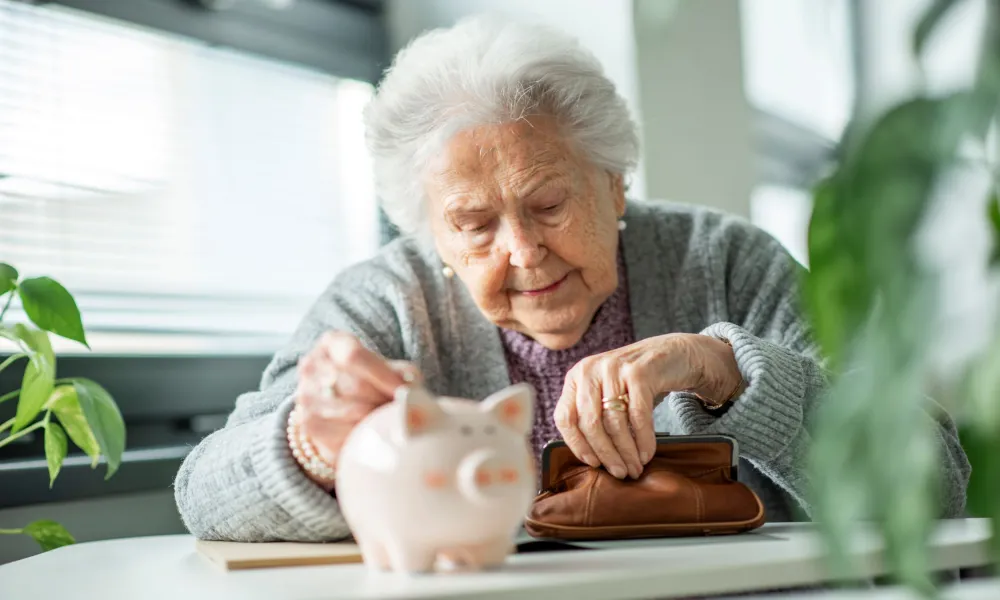
Inequalities faced by women in the labour market do not end when their working lives come to a close. Instead, they follow them into retirement, with the issue taking centre stage at a public hearing held in Brussels by the European Parliament’s Committees on Economic and Monetary Affairs and on Employment and Social Affairs.
The Chair of the Employment and Social Affairs Committee, Li Andersson, stressed that women’s pensions in the EU are, on average, approximately one quarter lower than men’s. She identified more frequent career interruptions, lower wages and lower participation in occupational pension schemes as the main contributing factors.
In the same context, as reported by SEK in its publication Ergatiki Foni, European Parliament President Roberta Metsola, in a recorded video message, highlighted pay inequalities, invisible work and persistent stereotypes that continue to restrict women’s professional and economic opportunities.
According to OECD figures, the gender pension gap fell from 28% in 2007 to 23% in 2024. However, this progress does not change the fact that millions of women continue to enter retirement with significantly lower incomes than men.
Lower earnings determine pension levels
As OECD Senior Policy Analyst Monika Queisser explained, a decisive factor in determining pension levels is the total income accumulated over a person's working life.
Differences in employment rates, working hours and hourly wages each contribute approximately one third to the overall pension gap, according to Queisser.
Periods during which women temporarily leave employment to care for children or elderly relatives are therefore particularly significant.
The OECD points out that pension credits for such periods can help limit the resulting losses. A simulation involving a mother of two children who takes five years away from work illustrates this. The rules governing mandatory pension schemes compensate for approximately half of the negative impact, provided she subsequently returns to full-time employment.
Survivors’ pensions also reduce the gap in mandatory pension schemes by approximately one third on average. Their importance is reflected in the fact that women account for 88% of beneficiaries.
However, the OECD representative stressed that meaningful and long-term progress requires inequalities to be addressed at the labour market level in the first place.
The cost of motherhood and unpaid care
The close relationship between family responsibilities and professional inequalities was highlighted by Lina Salanauskaite, a researcher at the European Institute for Gender Equality.
According to the figures she presented, the difference between women and men in the full-time equivalent employment rate stands at approximately 15 percentage points.
The gap becomes even more pronounced among couples with children, reaching 24 percentage points, compared with approximately five percentage points among couples without children.
The figures demonstrate that having children continues to affect women's participation in employment disproportionately, as they take on a greater share of everyday care responsibilities.
Salanauskaite also revealed that 8% of women in the EU experience economic violence, which can take the form of a partner preventing them from working or controlling household finances.
Among the proposals presented were a fairer distribution of parental leave, stronger provision of quality early childhood education and care services, and improved financial and pension literacy for both women and men.
Proposal for a universal state pension
The hearing also addressed the need to reconsider how pension systems account for periods of unpaid work.
Corinne Hutton, Executive Director of the National Women's Council of Ireland, said the EU pension gap stands at close to 25%, while in Ireland it ranges between 31% and 35%.
She proposed introducing a universal state pension independent of employment history and social security contributions, arguing that this would better recognise the contribution of people who devote a substantial part of their lives to unpaid care.
The Irish organisation's proposal provides for a pension equivalent to at least 34% of average earnings.
Hutton stressed that European pension systems continue to rely heavily on paid employment, earnings history and contributions, without always adequately accounting for career interruptions and part-time work linked to family responsibilities.
She also referred to the Pay Transparency Directive, emphasising that addressing the pension gap requires action well before retirement age.
Taxation as an additional barrier
Another dimension of the problem was highlighted by Ulrike Spangenberg, Head of the Reports Department on Gender Equality at the German Federal Foundation for Gender Equality, who focused on tax arrangements.
She explained that certain systems of joint taxation for couples may place a greater burden on the lower-earning partner, who is often the woman.
This can discourage both entry into the labour market and an increase in working hours.
The conclusion of the European Parliament hearing was clear: the gender pension gap does not emerge at retirement but develops gradually through inequalities accumulated throughout a woman's life.
Addressing it therefore requires more than changes to pension systems. It also calls for action on equal pay, employment opportunities, taxation and, above all, the distribution of responsibility for family care.