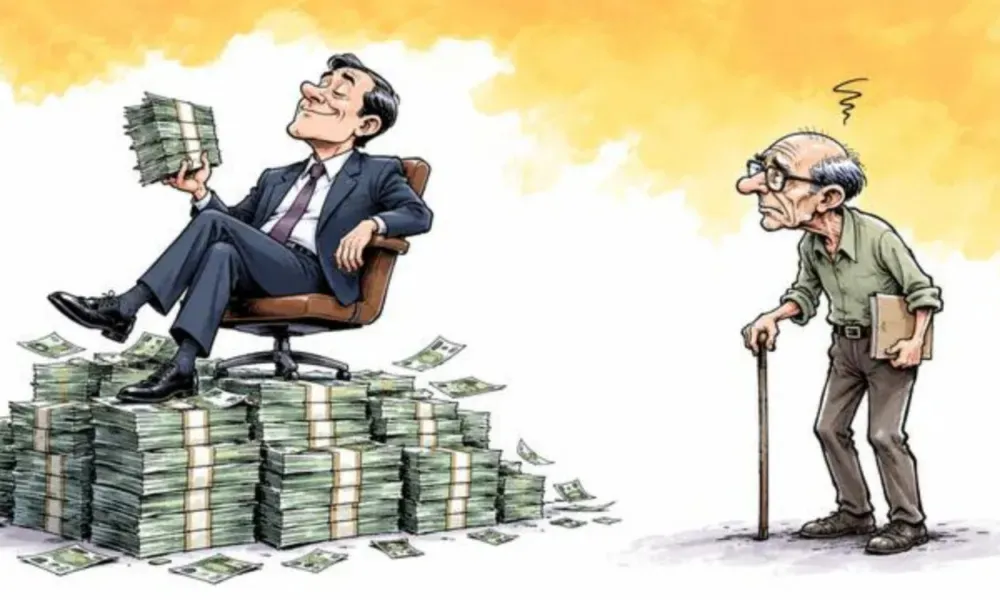
The increase in life expectancy and demographic pressures make it clear that the state pension alone will not be sufficient in the coming years to ensure a decent standard of living. In this context, strengthening the second pillar of pension provision and reforming Provident Funds has become an urgent necessity. However, discussions at the Labour Advisory Board have highlighted deep divisions among the social partners, leaving the government facing critical decisions. Differences and concerns also exist regarding the first pillar, which relates to low pensions.
Trade unions are insisting on preserving the existing framework for current provident funds, protecting acquired rights such as lump-sum benefit payments and borrowing facilities. At the same time, they are calling for a broader expansion of the institution through the creation of another universal fund, with the aim of covering the 77% of workers who currently remain outside the system, particularly low-paid and seasonal employees.
Employers, on the other hand, support maintaining the voluntary nature of the system through the provision of incentives, warning of the costs that new obligations would impose on businesses. At the same time, the Cyprus Chamber of Commerce and Industry has highlighted the risk of creating a "two-speed system" if existing funds are exempted, noting that pension adequacy is undermined if reserves continue to be paid out solely as lump sums rather than as regular monthly income. Both organisations favour the establishment of an independent supervisory authority.
Recognising that Provident Funds are a necessary supplement to retirement income, the government is seeking a "golden mean" between mandatory and voluntary participation so that neither side feels it has been forced into a complete retreat. At the same time, interventions by the Registrar of Provident Funds and the actuary of the International Labour Organization have underlined that maintaining two different regimes could delay the benefits of reform by as much as four decades.
To safeguard the living standards of future pensioners, a realistic compromise is required. Any solution must extend coverage to the entire workforce without dismantling acquired rights, while strengthening supervision and enhancing the long-term effectiveness and sustainability of the funds.