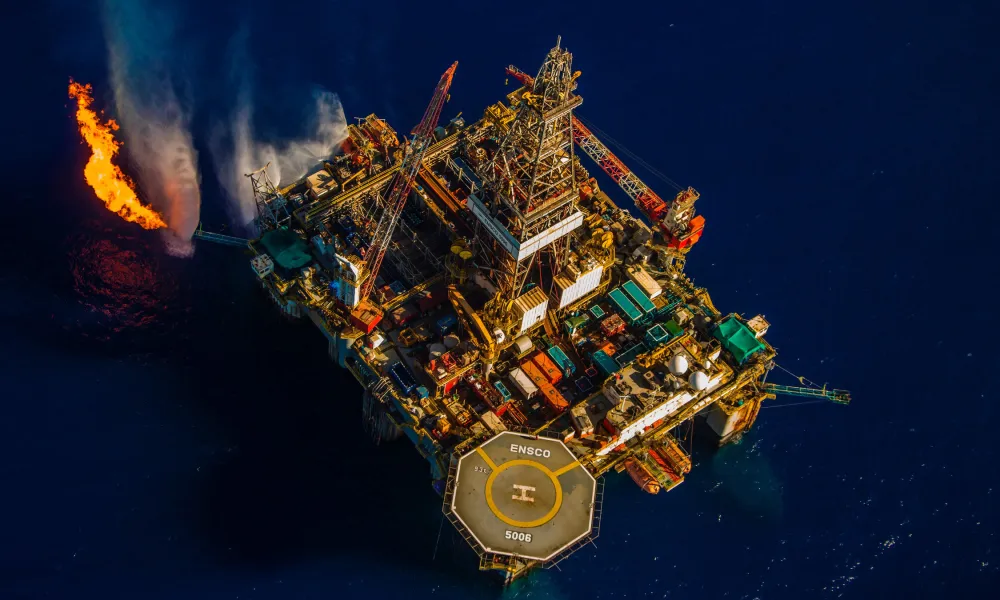
Cyprus is at odds with its Aphrodite partners over the cost of transporting natural gas from the reservoir across Egyptian waters, following a reported threefold increase in the proposed export pipeline tariff, according to industry specialist MEES.
In an article published yesterday, MEES reported that Chevron and its partners have proposed a tariff of around $3/mn Btu (British thermal units) to transport gas from the 3.7tcf (trillion cubic feet) Aphrodite reservoir through Egyptian waters. This is believed to be a significant increase from the previously envisaged figure of around $1/mn Btu, said the energy publication.
MEES East Med editor Peter Stevenson reported that Nicosia considers the charge excessive and has asked the Aphrodite partners to provide a more competitive offer.
In recent comments to Politis, Energy Minister Michalis Damianos had said Chevron was due to complete its Front-End Engineering Design (FEED) by December-January and make a Final Investment Decision (FID) on Cyprus’ first gas discovery within 2027, with the aim of taking first gas to market by 2031.
According to MEES, however, three issues remain pending: the export pipeline tariff; the signing of a binding Gas Sales Agreement (GSA) with Egypt’s natural gas holding company (EGAS); and final agreement on the Aphrodite-Ishai cross-border dispute with Israel.
Chevron making ‘steady progress’
Speaking to MEES, Chevron said it was making “steady progress towards delivering a technically robust and commercially viable project” with FEED and commercial negotiations ongoing but would not comment on specific commercial matters.
Upstream vs midstream revenues
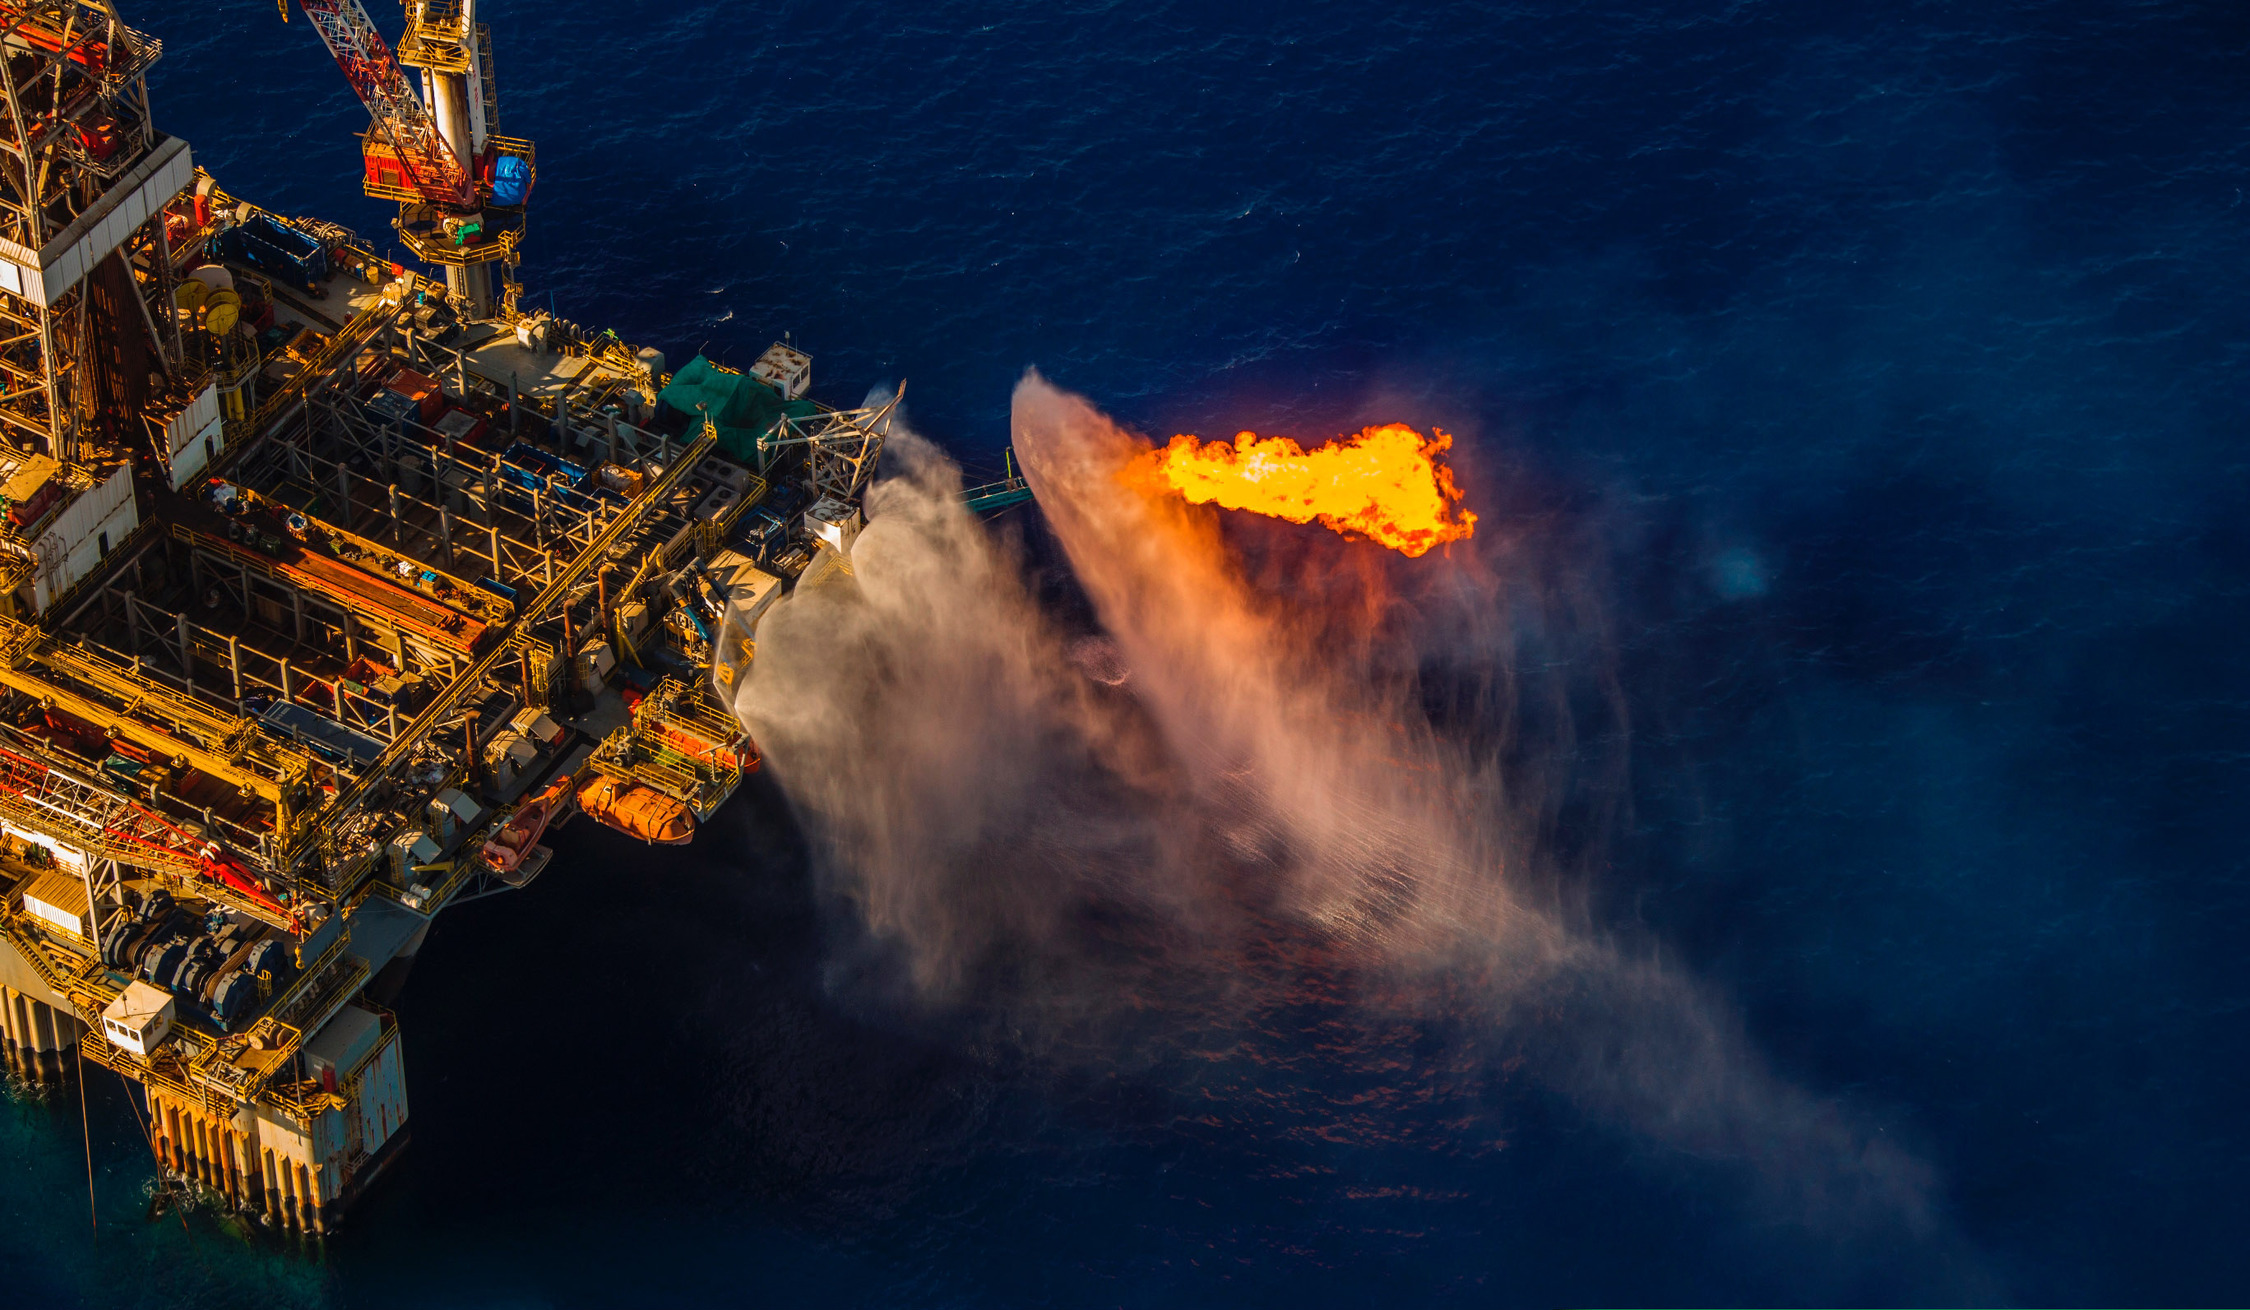
MEES explains that the gas in Block 12 of Cyprus’ Exclusive Economic Zone (EEZ) will be processed by a floating production unit (FPU) above the Aphrodite field and then transported to Port Said via subsea pipeline to connect to Egypt’s gas grid.
The part of the pipeline to be built and operated in Egyptian economic waters will be developed by a separate company, Aphrodite Midstream Company (AMC), that will reportedly include the three Aphrodite partners and an entity appointed by the Egyptian government.
MEES makes a distinction between ‘upstream’ and ‘midstream’ revenues. The former relates to revenue earned from finding and producing hydrocarbons while the latter concerns revenue from moving, processing, storing and transporting hydrocarbons.
Higher pipeline tariffs increase the cost of delivering gas to EGAS, which would raise earnings for the midstream company but could impact Cyprus’ own potential revenues from Aphrodite based on its production-sharing agreements, writes MEES. It notes that the Cypriot government has no direct involvement in the pipeline company.
The specialist publication calculated that if Aphrodite produces gas at its planned peak rate, generating sales of 700mn cfd (cubic feet per day), the difference between the $1/mn Btu and $3/mn Btu tariff could result in extra transportation charges of approximately $500mn/year when operating at maximum capacity.
MEES is careful to note this figure does not translate into an equivalent loss of Cyprus government revenues, but it does highlight the potential ramifications of the ongoing negotiations.
Potential delays
The dispute over the pipeline tariff appears to be having a knock-on effect on talks to sign a binding Gas Sales Agreement that would set the framework for EGAS to purchase all of Aphrodite’s recoverable gas. Egyptian officials have expressed a desire to finalise the GSA before next week’s Mediterranean Offshore Conference in Alexandria, on 20-22 October.
According to MEES, however, Nicosia seeks clarity on the transportation arrangements before proceeding with GSA negotiations.
Regarding drawn-out talks on resolving the Aphrodite-Ishai dispute over the part of the gas reservoir that extends into Israeli waters, CNA reported that talks were held on Wednesday between technical experts and legal advisers of Cyprus and Israel, along with the Aphrodite and Ishai operators.
Despite an effort to wrap up the long-running negotiations before Israeli elections on 27 October, Damianos told Politis last week that he was not hopeful the deadline would be met.
FID on time?
MEES notes that under the February 2025 amendment to the production-sharing contract agreed with Cyprus, the Aphrodite partners have approximately until June 2027 to take a Final Investment Decision (FID).
It remains to be seen how Aphrodite operator Chevron and its partners will respond to the government’s call for revision of the latest tariff proposal and whether that can unlock the door to a GSA, completion of FEED, and taking FID. Then of course, lingering in the background, is the perennial Ishai dispute and its pending resolution.